Every six weeks or so, a small committee in Washington, Frankfurt or London sits down to make a decision that moves trillions of dollars before lunch. Whether to cut interest rates, hold them, or — still not impossible — raise them again has become the defining question of the world economy, and the honest answer from most central bankers is that they are walking a narrow line with fog on both sides.
The dilemma in plain terms
Cut too early, and borrowing costs fall while inflation is still smouldering — inviting a second wave of price rises that would be far harder to extinguish. Hold too long, and the medicine becomes the disease: mortgages stay punishing, businesses shelve investment, and unemployment creeps up. Officials at the Federal Reserve describe their stance as “data dependent”, a phrase markets have learned to parse like scripture, because a single inflation report can reprice everything from government bonds to the exchange rate within minutes.
The politics are as delicate as the economics. Rate decisions land in the middle of election cycles, housing crises and trade disputes, and central banks guard their independence jealously precisely because the temptation for governments to demand cheaper money is permanent.
Why markets hang on every syllable
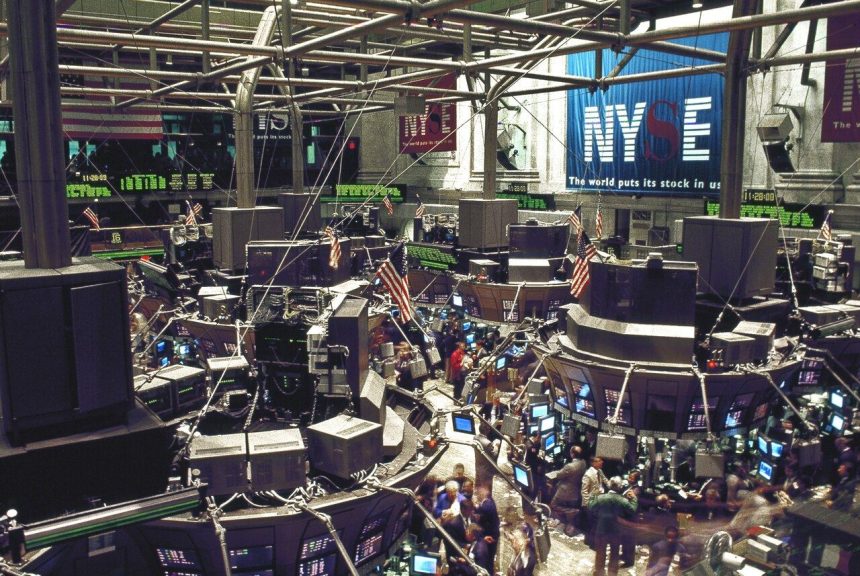
Traders do not only trade the decision; they trade the wording. A single adjective dropped from a central bank statement can signal that a cut has moved closer or further away, and futures markets translate that signal into prices instantly. Our Business desk tracks how those expectations ripple into currencies, commodities and the borrowing costs that eventually reach households.
The International Monetary Fund has repeatedly warned that the last stretch of disinflation is the hardest, because the easy gains — falling energy prices, unclogged supply chains — have already been banked. What remains is sticky services inflation, driven by wages, rents and insurance, which responds slowly to rate policy.
What households should watch
For savers and borrowers, the practical signals are unglamorous: the trend in core inflation, wage growth, and how officials talk about risk. When central bankers start worrying aloud about jobs rather than prices, the turning point is usually near. Until then, the narrow line holds — and so, mostly, do rates.
The global dimension complicates every national decision. When the largest economies move at different speeds, exchange rates absorb the strain, and a central bank that cuts bravely ahead of its peers may import fresh inflation through a weaker currency. Emerging-market central banks watch the Federal Reserve the way sailors watch a lighthouse — not for instructions, but because the weather changes around it. Capital flows toward yield, and a surprise in Washington can become a funding crisis in a capital city that has done nothing wrong.
There is also the matter of what rates cannot fix. Housing shortages, energy transitions and labour mismatches are supply problems; interest rates are a demand tool, and applying a demand tool to a supply problem means squeezing the parts of the economy that were never the issue. That tension — between the one lever central banks have and the many problems they are blamed for — is why their statements have become exercises in deliberate ambiguity, and why the narrow line keeps getting narrower.